If you miss your Medicare enrollment window, you can end up with a permanent monthly penalty and a gap in health coverage that lasts for months. Most people get one clear shot at signing up on time. Once that window closes, getting back into the system takes more than a phone call. This article walks through exactly what happens after a missed Medicare enrollment window, how the penalties are calculated, and what your options look like if you are already past the deadline.
Understanding Your Medicare Enrollment Window
Your Initial Enrollment Period is the main Medicare enrollment window most people rely on. It starts three months before you turn 65, includes your birthday month, and runs three more months after that, for a seven month span in total.
If you are already collecting Social Security, you are usually enrolled in Medicare automatically, so this window is not something you have to track yourself. If you are not collecting benefits yet, you need to sign up on your own, and that is exactly where a lot of people miss the Medicare enrollment window without realizing it.
Missing the Medicare Enrollment Window: What Happens Next
Once your Medicare enrollment windows close without action, two things typically happen. First, you are locked out of Medicare Part B and Part D until the next General Enrollment Period, which runs from January 1 to March 31 each year. Second, coverage you sign up for during that later period usually does not start right away.
That gap can stretch close to a full year, depending on how far past your window for Medicare enrollment you are when you finally apply. During that stretch, you are typically responsible for your own medical costs out of pocket.
This is one of the most expensive mistakes in retirement planning, precisely because it is so avoidable. A single missed deadline can mean months of paying full price for doctor visits, prescriptions, and hospital stays with no help from Medicare at all. Setting a calendar reminder for three months before your 65th birthday is a small step that prevents a very costly problem later.
Part B Penalties for a Missed Medicare Enrollment Window
Calculating the Part B Penalty After a Missed Medicare Enrollment Window
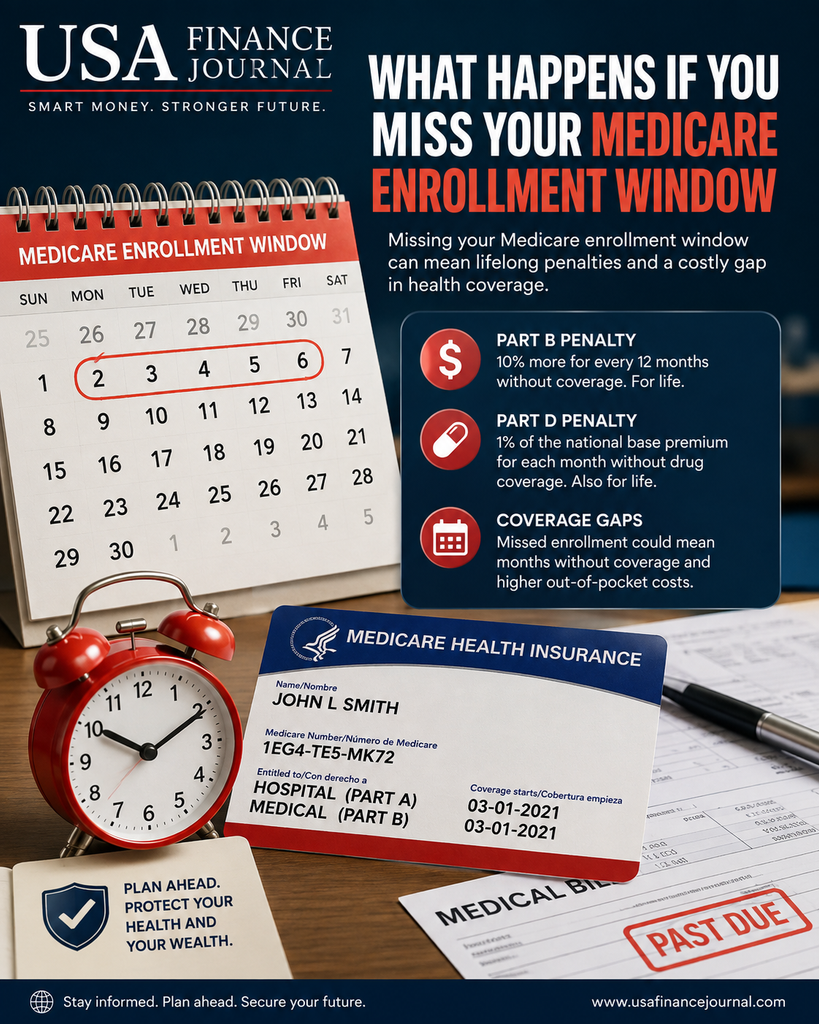
If you miss your sign up date and do not qualify for a Special Enrollment Period, Part B adds a 10 percent premium penalty for every full 12 month period you went without coverage. This penalty applies for as long as you keep Part B, which in most cases means for life.
Here is a simple example using a standard premium of $185 a month. The table below shows how the penalty stacks up over time.
| Time without Part B | Penalty added | New monthly premium |
|---|---|---|
| 12 months | 10% | $203.50 |
| 24 months | 20% | $222.00 |
| 36 months | 30% | $240.50 |
These figures are for illustration only. Always check current numbers on Medicare.gov, since premiums and penalty amounts are updated each year.
Notice that the penalty is based on full 12 month blocks, not partial months. Going 13 months without coverage still only counts as one full block, so it can pay off to enroll even a few weeks before crossing into a new 12 month period. Small timing decisions like this can save hundreds of dollars a year over the course of retirement.
Part D Penalties When You Miss Your Medicare Enrollment Window
Part D works a little differently. If you go 63 days or more without creditable prescription drug coverage after your enrollment window ends, you will owe a separate penalty. It is calculated as 1 percent of the national base beneficiary premium for every month you went without coverage, and that amount gets added to your monthly Part D premium.
Unlike the Part B penalty, this one grows slowly month to month, but it also never goes away on its own. Over a couple of decades of retirement, a Part D penalty tied to a missed Medicare enrollment window can add up to real money.
The national base beneficiary premium changes every year, so the exact dollar cost of the penalty shifts too. What stays the same is the math behind it: the longer you wait to get prescription drug coverage, the more it costs you every single month afterward, without exception.
Special Enrollment Periods vs a Missed Medicare Enrollment Window
Not everyone who misses the standard sign up date is stuck with penalties. If you or your spouse still have coverage through an employer with 20 or more employees, you likely qualify for a Special Enrollment Period, which protects you from the usual costs of a missed sign up.
That Special Enrollment Period lasts eight months after the employer coverage or the job ends, whichever comes first. It runs on a separate clock from the standard Medicare enrollment window, so it is worth checking with your HR department if you are still working past 65.
Keep the paperwork that proves you had employer coverage the whole time, since Medicare may ask you to show it when you enroll under this rule. Losing that documentation is one of the more common reasons people end up disputing a penalty they should never have owed in the first place.
Coverage Gaps After Missing Your Medicare Enrollment Window
Penalties are not the only cost that comes with missing your sign up date. There is also the coverage gap itself. If you miss the Initial Enrollment Period and wait for the General Enrollment Period instead, your coverage might not start until July of that year.
For anyone living on a fixed retirement income, a gap like that is a real financial strain, not just an inconvenience. It is worth planning around your Medicare enrollment window well before you turn 65, not after.
Some people bridge the gap with COBRA or marketplace coverage, but both options tend to cost more than Medicare and are not guaranteed to line up perfectly with the date your Medicare coverage finally starts. Treating the sign up date as fixed, rather than flexible, is the simplest way to avoid this problem altogether.
How to Get Back on Track After a Missed Medicare Enrollment Window
If you have already missed your Medicare enrollment window, mark your calendar for the next General Enrollment Period, January 1 through March 31, and apply as soon as it opens to shorten your coverage gap.
It also helps to map your full retirement income and health costs together, since Medicare premiums and penalties are only one piece of the puzzle. You can factor a missed Medicare enrollment window into your broader plan with our Retirement Corpus Calculator, which shows how a late start affects your monthly budget over time.
Bottom Line: A missed Medicare enrollment window usually means a lasting premium penalty and a coverage gap of several months, but Special Enrollment Periods and careful planning can soften the impact. Mark your dates early, and act the moment the next enrollment window opens.
This is for informational purposes only and isn’t financial, tax, or legal advice.

Raghu Shekar writes about personal finance, banking, Medicare, and retirement planning at SimpleUSAFinance. His goal is simple: break down the numbers people actually need — no jargon, no sales pitch — so readers can make their own decisions with confidence. When he’s not writing, he’s usually digging through the latest rate changes, tax brackets, or Medicare updates to keep the site’s calculators and guides current.