Most retirees don’t live on one paycheck. They live on several smaller ones stitched together. If you want to estimate retirement income from multiple sources without guessing, you need one worksheet, a few current numbers, and a simple order of operations. This guide walks through exactly how to do that, using 2026 figures.
Why You Need to Estimate Retirement Income From Multiple Sources
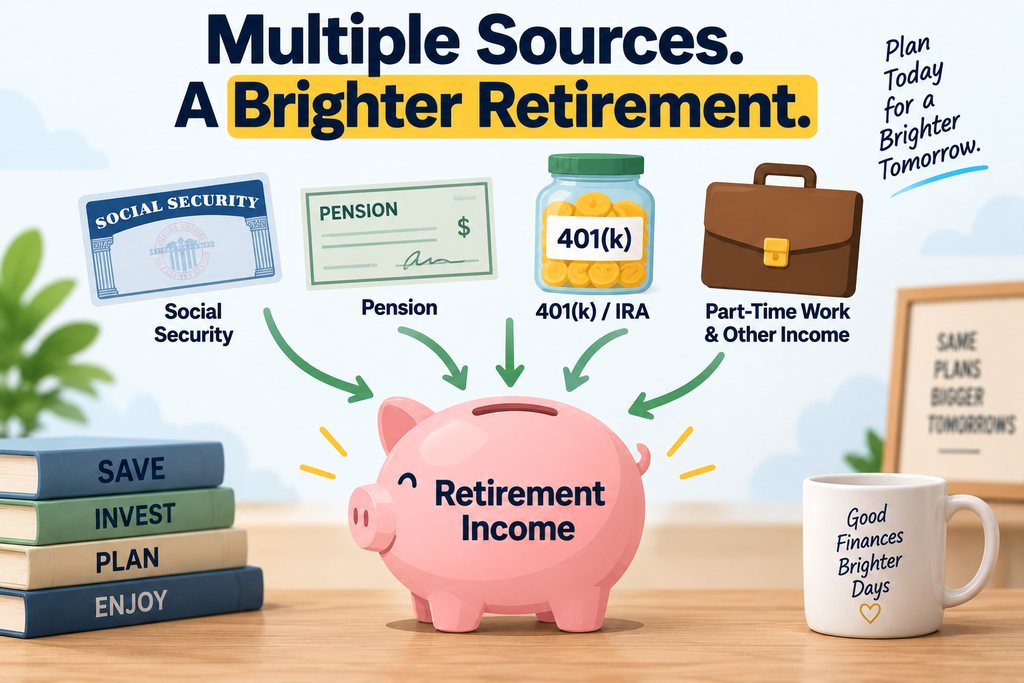
A single number on a 401(k) statement doesn’t tell you what your life will look like at 67. Retirement income usually blends Social Security, a pension if you have one, withdrawals from retirement accounts, and maybe part-time work or rental income. To estimate retirement income from multiple sources accurately, you have to look at each stream on its own terms. Some are guaranteed for life, some depend on the market, and some are taxed differently than others.
Skipping this step is why so many people are surprised in their first year of retirement. They knew their savings balance. They didn’t know their monthly cash flow — and that gap is exactly what you close when you estimate retirement income from multiple sources ahead of time.
The Core Idea: Stack, Then Subtract
The simplest way to estimate retirement income from multiple sources is to stack every income stream by month, then subtract taxes and known expenses. Add everything up gross first, then work down to what actually lands in your checking account.
Step 1: List Every Retirement Income Source
Before you can estimate retirement income from multiple sources, write down everything that could pay you after you stop working:
- Social Security retirement benefits
- Traditional pension (if your employer offers one)
- 401(k), 403(b), or similar workplace account withdrawals
- Traditional and Roth IRA withdrawals
- Taxable brokerage account income
- Part-time work or consulting
- Rental income
- Annuity payments
Most people have three or four of these. Very few have all eight, and that’s fine. The point of this list is simply to make sure nothing is left out before you try to estimate retirement income from multiple sources for the year ahead.
Step 2: Get a Real Social Security Estimate
Social Security is usually the largest guaranteed piece, so get this number right first. As of January 2026, the average monthly benefit for a retired worker is about $2,064, following a 2.8% cost-of-living adjustment. Your own benefit could be far higher or lower depending on your earnings history and the age you claim.
Create a free account at ssa.gov to pull your actual estimated benefit at age 62, full retirement age, and age 70. This single step does more to help you estimate retirement income from multiple sources correctly than any spreadsheet trick, because Social Security is inflation-adjusted and lasts as long as you do. Skip it, and every later attempt to estimate retirement income from multiple sources will be built on a guess instead of a real number.
Step 3: Add Pension Income, If You Have One
If you’re one of the shrinking number of workers with a traditional pension, request a benefit estimate from your plan administrator. Ask specifically whether the payment is a fixed monthly amount for life, whether it includes a cost-of-living adjustment, and what happens to it if you die before your spouse. If your plan offers a one-time lump sum instead of monthly payments, run the numbers with our Lump-Sum vs. Annuity Calculator before you decide, since that choice permanently changes how you estimate retirement income from multiple sources going forward.
Step 4: Estimate Withdrawals From Retirement Accounts
Using a Safe Withdrawal Rate
For 401(k), IRA, and brokerage balances, a common starting point is a 3.5% to 4% annual withdrawal rate, adjusted for your time horizon and risk tolerance. On a $500,000 balance, that’s roughly $17,500 to $20,000 per year, or about $1,460 to $1,670 per month. This is usually the hardest part of learning how to estimate retirement income from multiple sources, because markets move and no rate is guaranteed.
Keep 2026 account rules in mind if you’re still saving. According to the IRS, the 401(k) employee contribution limit is $24,500 for 2026, and the IRA limit is $7,500, with an additional catch-up amount available if you’re 50 or older. Required minimum distributions from most retirement accounts generally must begin at age 73, which affects when this income stream turns on.
Step 5: Put It All Together in One Table
Here’s a simplified example that shows how to estimate retirement income from multiple sources for a single retiree:
| Income Source | Monthly Amount |
|---|---|
| Social Security | $2,064 |
| Small pension | $600 |
| 401(k)/IRA withdrawals (4% rule) | $1,500 |
| Part-time consulting | $500 |
| Total monthly income | $4,664 |
This kind of table is the fastest way to estimate retirement income from multiple sources at a glance, and it makes gaps obvious immediately. If your monthly expenses run $5,200, you can see the shortfall before it becomes a problem. Rebuilding this table with your own numbers is, in practice, the whole exercise of learning how to estimate retirement income from multiple sources.
Step 6: Adjust for Taxes and Timing
Not every dollar you estimate retirement income from multiple sources arrives untaxed. Traditional 401(k) and IRA withdrawals are generally taxed as ordinary income. Up to 85% of Social Security benefits can be taxable depending on your total income. Roth withdrawals and returned principal from a brokerage account are usually not taxed the same way, so build a rough tax rate into your monthly total instead of assuming every source pays the same amount.
How Often Should You Update the Estimate?
Balances change, benefit amounts get adjusted for inflation, and tax rules shift almost every year, so it’s worth revisiting how you estimate retirement income from multiple sources on an annual basis. A once-a-year check-in, ideally right after you receive your Social Security COLA notice and your year-end account statements, keeps your numbers close to reality instead of years out of date. Retirees who estimate retirement income from multiple sources annually rarely get caught off guard by a shortfall mid-year.
Common Mistakes People Make
These are the most frequent errors people run into when they try to estimate retirement income from multiple sources for the first time:
- Assuming Social Security alone will cover the bills
- Forgetting that pensions without a cost-of-living adjustment lose value over time
- Using a withdrawal rate that’s too aggressive for a 25- to 30-year retirement
- Ignoring required minimum distributions and the taxes that come with them
- Not updating the estimate every year as balances and benefit amounts change
Avoiding these five mistakes is most of what it takes to estimate retirement income from multiple sources with confidence.
Bottom Line
Learning how to estimate retirement income from multiple sources comes down to listing every stream, pricing each one with current numbers, and adding it up net of taxes rather than gross. Do this once a year, and you’ll always know where you stand before retirement, not after.
This is for informational purposes only and isn’t financial, tax, or legal advice.

Raghu Shekar writes about personal finance, banking, Medicare, and retirement planning at SimpleUSAFinance. His goal is simple: break down the numbers people actually need — no jargon, no sales pitch — so readers can make their own decisions with confidence. When he’s not writing, he’s usually digging through the latest rate changes, tax brackets, or Medicare updates to keep the site’s calculators and guides current.