If your current plan isn’t working out, you can switch back to Original Medicare, but only during specific windows each year. This guide walks through exactly when you’re allowed to switch back to Original Medicare, what happens to your prescription drug coverage, why timing affects your Medigap options, and what the cost trade-off actually looks like. By the end, you’ll know which window fits your situation and what to check before you make the move.
When You Can Switch Back to Original Medicare
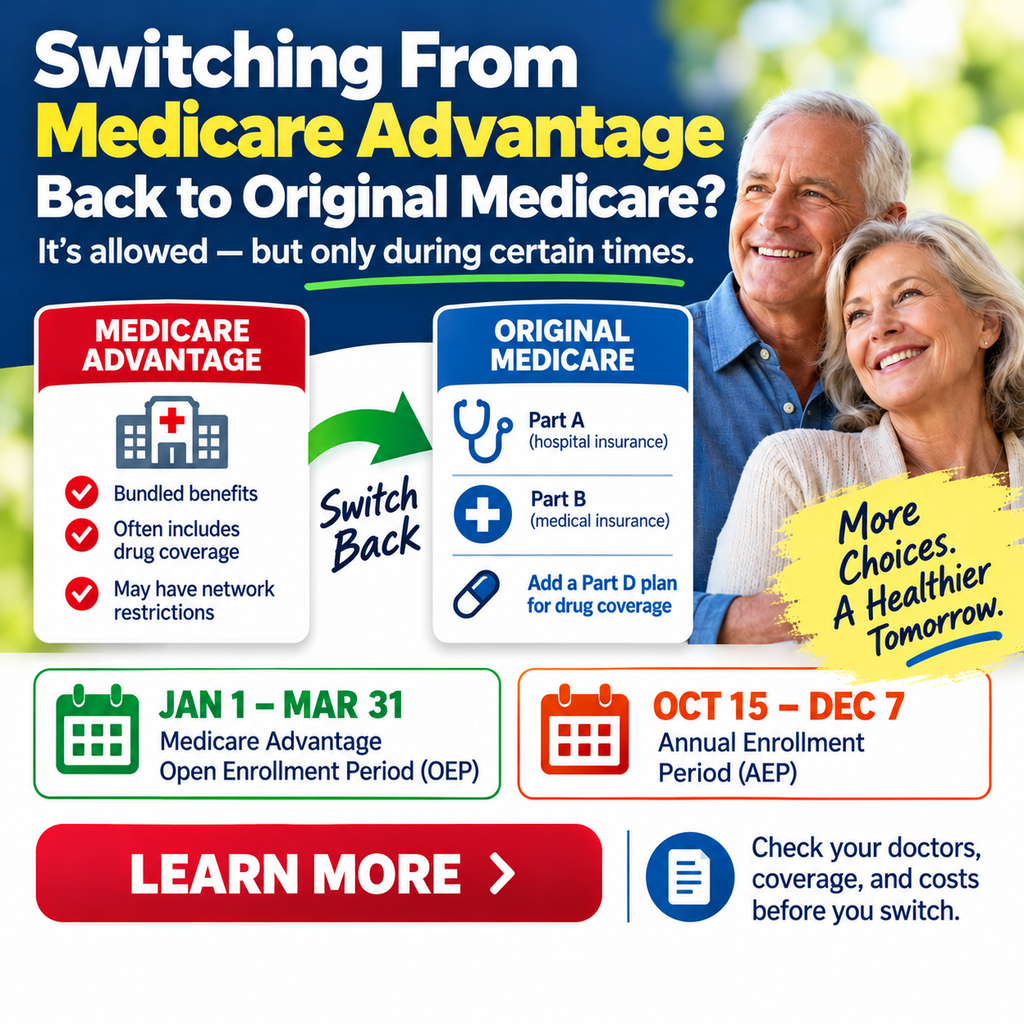
There are two main windows to switch back to Original Medicare. The first is the Medicare Advantage Open Enrollment Period (OEP), which runs January 1 through March 31 every year. The second is the Annual Enrollment Period (AEP), which runs October 15 through December 7.
Outside these two windows, you generally need a Special Enrollment Period to switch back to Original Medicare. We’ll cover those exceptions below, since they’re often the most useful option for people who need to leave a plan mid-year.
Enrollment Windows at a Glance
| Window | Dates | What It Allows |
|---|---|---|
| OEP | Jan 1 – Mar 31 | One switch back to Original Medicare (plus a Part D plan) |
| AEP | Oct 15 – Dec 7 | Switch back to Original Medicare, effective Jan 1 |
| Special Enrollment Period (SEP) | Varies by qualifying event | Switch back outside the above windows if you qualify |
The Medicare Advantage Open Enrollment Period (OEP) Explained
The OEP is built specifically for people already enrolled in a Medicare Advantage plan. During this 90-day window, you can switch back to Original Medicare as a one-time move. You can also use the OEP to switch to a different Medicare Advantage plan instead, but you only get one change, not both.
If you switch back to Original Medicare during the OEP, you’re also allowed to enroll in a standalone Part D drug plan at the same time. Your new coverage typically starts on the first day of the month after you make the change.
What the OEP Does Not Allow
The OEP is not a general enrollment window. You cannot use it to move from Original Medicare into a Medicare Advantage plan, and you cannot use it to switch between two standalone Part D plans if you’re already on Original Medicare. It exists only for current Medicare Advantage members who want a second chance to fix a plan they picked the previous fall.
Special Enrollment Periods That Let You Switch Anytime
Several Special Enrollment Periods (SEPs) let you switch back to Original Medicare outside the OEP and AEP windows. The most useful for many people is the Federal Trial Right: if you joined a Medicare Advantage plan for the first time when you turned 65, and you switch back to Original Medicare within 12 months, you have a one-time federal right to buy any Medigap policy sold in your state without medical underwriting.
Other SEPs that let you switch back to Original Medicare include moving out of your plan’s service area, losing employer coverage, your plan losing its Medicare contract, or qualifying for Extra Help or a Medicare Savings Program. A 5-star Special Enrollment Period also exists if a 5-star Medicare Advantage plan is available in your area, though that SEP is typically used to switch into a plan rather than out of one.
What Happens to Your Drug Coverage When You Switch Back
When you switch back to Original Medicare, you lose whatever drug coverage was bundled into your Medicare Advantage plan. Original Medicare on its own does not include prescription drug coverage, so you’ll need a standalone Part D plan to avoid a gap.
Here’s a concrete example using 2026 figures. The maximum Part D deductible for 2026 is $615, up from $590 in 2025. After you meet the deductible, you generally pay a share of your drug costs until your total out-of-pocket spending hits $2,100 for the year. Once you cross that $2,100 threshold, your plan covers approved prescriptions in full for the rest of the calendar year. These numbers vary somewhat by plan, so confirm your specific plan’s deductible before you switch back to Original Medicare.
If you go even one day without creditable drug coverage after you switch back to Original Medicare, you risk a Part D late enrollment penalty that permanently adds to your premium — so lining up a standalone plan to start the same day your Medicare Advantage coverage ends matters as much as the decision to switch itself.
Medigap Guaranteed Issue Rights: Why Timing Matters
This is the part people miss most often when they switch back to Original Medicare. Original Medicare doesn’t cap your annual out-of-pocket costs on its own, which is why many people pair it with a Medigap policy. But Medigap insurers can require medical underwriting outside specific guaranteed-issue windows.
If you’re within your 12-month Federal Trial Right, you can buy any Medigap policy in your state regardless of health history. Some states also offer their own guaranteed-issue protections beyond the federal minimum — for example, a handful of states require insurers to offer at least one Medigap plan on a guaranteed-issue basis during an annual “birthday rule” or open window, regardless of a federal trial right — so it’s worth checking your state’s specific rules. Outside a guaranteed-issue window, an insurer can review your health history and either deny you coverage or charge a higher premium, which can make it costly to switch back to Original Medicare if you wait too long.
Weighing the Cost Trade-Off
Switching back to Original Medicare usually means trading a low or $0 Medicare Advantage premium for three separate costs: Original Medicare’s Part B premium (which you already pay either way), a standalone Part D premium, and a Medigap premium if you add one. In exchange, you generally gain broader provider access and predictable, capped out-of-pocket costs rather than a plan-specific maximum that resets annually.
For many retirees, the Medigap premium is the deciding factor — it can range widely by state, age, and plan letter, so getting an actual quote before you commit to switching back to Original Medicare is far more useful than relying on national averages.
Steps to Take Before You Switch Back
Before you switch back to Original Medicare, a few checks can save you real money and hassle:
- Confirm your doctors and hospitals accept Original Medicare in your area.
- Get a Medigap quote first, so you know your guaranteed-issue status before you disenroll.
- Compare standalone Part D plans against your current medication list.
- Remember Original Medicare doesn’t cover routine dental, vision, or hearing, benefits many Medicare Advantage plans include.
- If your income is on the higher side, check where you fall using our free IRMAA Calculator, since your Part B and Part D premiums can shift once you switch back to Original Medicare.
Frequently Asked Questions
Can I switch back to Original Medicare more than once a year? No. Outside a qualifying Special Enrollment Period, you’re limited to one change during the OEP and one during the AEP each year — you can’t use the OEP repeatedly within the same 90-day window.
Will I be denied a Medigap policy if I have a pre-existing condition and I’m outside a guaranteed-issue window? Possibly. Insurers can medically underwrite Medigap applications outside guaranteed-issue periods, which means they can deny coverage or charge more based on your health history, though a small number of states limit this practice further than federal law requires.
Does switching back to Original Medicare affect my Social Security or IRMAA surcharge? No, switching plans doesn’t change your IRMAA bracket, since that surcharge is based on your reported income from two years prior, not which type of Medicare coverage you choose.
Bottom Line
You can switch back to Original Medicare during the January to March OEP, the fall AEP, or through a handful of Special Enrollment Periods if you qualify. The bigger decision usually isn’t whether you can switch back to Original Medicare, but when, since your Medigap guaranteed-issue rights and drug coverage gap depend heavily on timing.
This is for informational purposes only and isn’t financial, tax, or legal advice.

Raghu Shekar writes about personal finance, banking, Medicare, and retirement planning at SimpleUSAFinance. His goal is simple: break down the numbers people actually need — no jargon, no sales pitch — so readers can make their own decisions with confidence. When he’s not writing, he’s usually digging through the latest rate changes, tax brackets, or Medicare updates to keep the site’s calculators and guides current.