Weighing joint bank account pros and cons usually happens right after a couple moves in together, gets married, or starts planning a shared budget. It feels like a simple decision, but the fine print matters more than most people realize.
This guide covers the real joint bank account pros and cons, walks through a concrete numbers example, and flags the one mistake that trips up couples who otherwise do everything right. By the end, you should be able to weigh joint bank account pros and cons for your own situation with confidence.
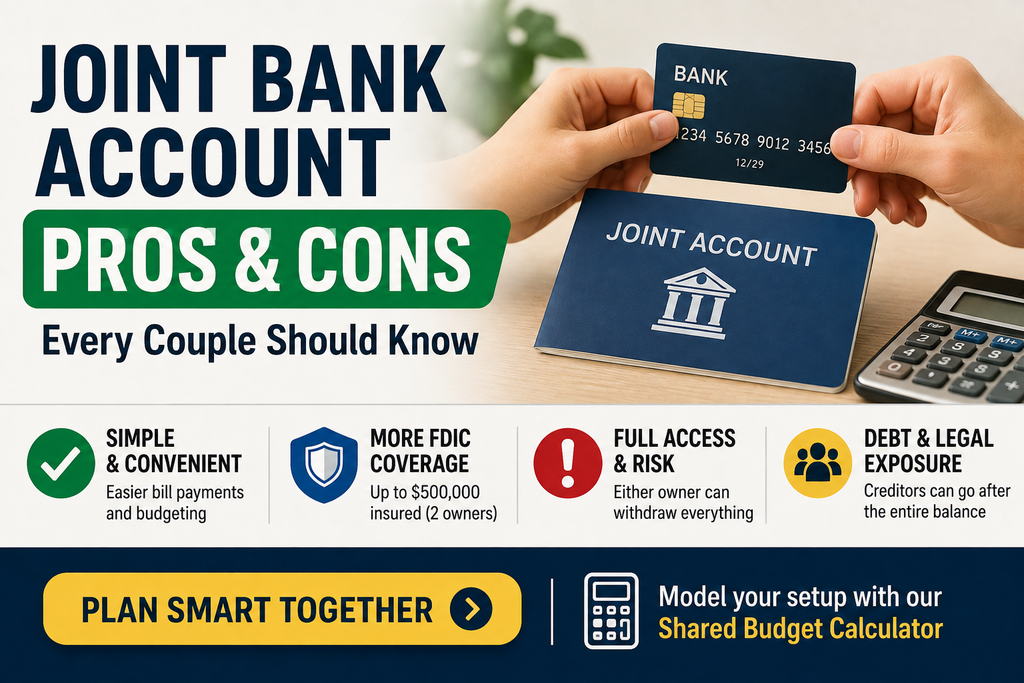
The Real Joint Bank Account Pros and Cons List
On the plus side, a shared account makes paying rent, splitting bills, and tracking household spending far simpler than juggling transfers between two individual accounts. Survivorship rights are another advantage, since most joint accounts pass directly to the surviving co-owner without going through probate.
On the downside, joint bank account pros and cons include a loss of independent control. Every co-owner typically has full access to withdraw the entire balance, not just their agreed-upon share, and that access exists whether or not both people are equally responsible for how the money is spent.
Weighing joint bank account pros and cons also means thinking about credit history. Most joint checking and savings accounts do not report to credit bureaus at all, but joint credit products tied to the same relationship, like a shared credit card, can affect both people’s scores if payments are missed.
The FDIC Side of Joint Bank Account Pros and Cons
One underrated benefit shows up in deposit insurance. According to FDIC guidance on insured deposits, coverage for a joint account is calculated per co-owner, and the balance of a joint account can exceed $250,000 and still be fully insured.
For a couple with two equal co-owners, that generally means up to $500,000 in FDIC coverage at the same bank, compared to $250,000 for an individual account. This is one of the more overlooked joint bank account pros and cons, since most people only think about convenience and forget insurance limits entirely.
A Simple Table on Joint Bank Account Pros and Cons
| Factor | Individual Account | Joint Account (2 owners) |
|---|---|---|
| FDIC coverage at one bank | $250,000 | Up to $500,000 |
| Withdrawal access | One person only | Both people, full balance |
| Passes to survivor without probate | No | Yes, typically |
| Exposure to a co-owner’s debt collectors | No | Often yes |
The Mistake Most Couples Make in Joint Bank Account Pros and Cons
Here is where the joint bank account pros and cons conversation usually goes wrong. Couples assume that opening a shared account somehow splits ownership into neat, tracked percentages, like each person owns exactly what they deposited.
That is not how it works. In most states, each co-owner has an equal, undivided right to the full balance, and banks generally treat the money as fully accessible to either person regardless of who put it in.
This single misunderstanding sits at the center of most joint bank account pros and cons regret. Couples rarely discover the gap between assumed ownership and actual legal access until a breakup, a lawsuit, or a creditor forces the question.
The bigger risk hides in what happens if one partner runs into financial trouble. If a creditor gets a judgment against one co-owner, or the IRS pursues back taxes, joint bank account pros and cons research consistently shows that the entire account balance can be frozen or garnished, not just that person’s assumed half.
Weighing Joint Bank Account Pros and Cons Before You Combine Everything
A common and much safer approach is a hybrid setup rather than an all-or-nothing decision. Couples keep individual accounts for personal spending and any pre-relationship debt exposure, while using a joint account only for shared expenses like rent, utilities, and groceries.
This structure captures most of the joint bank account pros and cons upside, like simpler bill splitting and survivorship benefits, while limiting how much of your combined savings sits exposed to one partner’s individual financial risk.
Working through joint bank account pros and cons with your partner ahead of time, rather than after a problem shows up, is what actually prevents the mistake described above.
A few practical steps before opening a shared account:
- Agree in writing on what expenses the joint account covers and what stays separate
- Check whether either partner has existing debt, judgments, or tax liens that could expose a shared balance
- Confirm how much you would keep below the $250,000 per co-owner FDIC threshold if your combined savings are large
- Review the account’s overdraft and joint liability terms directly with your bank before signing
If you want to see how splitting expenses between a joint and individual setup affects your monthly numbers, run your own joint bank account pros and cons scenario with our shared budget calculator, which lets you model both structures side by side.
Joint vs. Individual Accounts: Which Wins on Paper
When people search joint bank account pros and cons, they are often really asking whether joint or individual is simply better. Neither wins outright, because the right answer depends on how much financial risk each partner is bringing into the relationship.
For couples with similar income, no significant debt, and full trust in shared spending habits, the convenience side of joint bank account pros and cons usually wins. For couples where one partner has meaningful individual debt or income disparity, a hybrid or fully separate structure often protects both people better.
There is no universal right answer here, which is exactly why reviewing joint bank account pros and cons together, as a couple, matters more than following a generic rule you read online.
For more detail on how banks structure this coverage, the FDIC’s official joint account rules define a joint account as a deposit owned by two or more individuals, insured up to $250,000 per co-owner based on that person’s combined interest in all joint accounts at the same bank. The Consumer Financial Protection Bureau also publishes guidance on how banks handle liability and access on shared accounts, which is worth reading before you sign anything.
Bottom Line
Joint bank account pros and cons come down to convenience and shared insurance benefits weighed against full mutual access and shared liability risk. Before combining everything, talk through each partner’s individual debt exposure and consider a hybrid setup that keeps some money separate.
This is for informational purposes only and isn’t financial, tax, or legal advice.

Raghu Shekar writes about personal finance, banking, Medicare, and retirement planning at SimpleUSAFinance. His goal is simple: break down the numbers people actually need — no jargon, no sales pitch — so readers can make their own decisions with confidence. When he’s not writing, he’s usually digging through the latest rate changes, tax brackets, or Medicare updates to keep the site’s calculators and guides current.