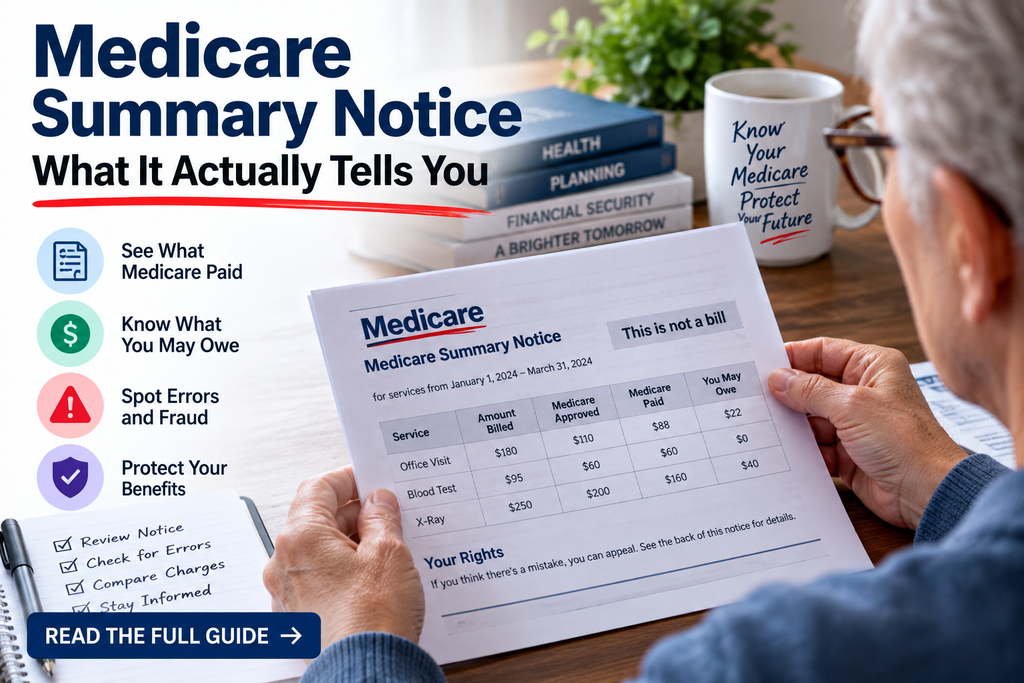
Every three months, a Medicare Summary Notice shows up in your mailbox, and for a lot of people it goes straight into a drawer unopened. That’s a mistake. Your Medicare Summary Notice isn’t a bill, but it’s the clearest record you’ll get of what Medicare paid, what your providers billed, and what you might still owe. Understanding it takes about ten minutes and can save you real money.
What Is a Medicare Summary Notice?
A Medicare Summary Notice, often shortened to MSN, is a quarterly statement mailed to anyone enrolled in Original Medicare (Part A and Part B). It lists every claim processed for you in the past three months: the date of service, the provider, what was billed, what Medicare approved, and what you may still owe.
Think of it as a receipt after the fact. Your doctor’s office already got paid or denied weeks earlier. The Medicare Summary Notice just tells you, on paper, what happened.
Why Your Medicare Summary Notice Isn’t a Bill
This trips people up constantly. A Medicare Summary is not an invoice, and you should never mail a payment in response to one. If you owe money, that request comes separately, from your provider or from Medicare itself.
What the notice does give you is a paper trail. If a provider ever bills you directly for more than the notice shows you owe, that’s your evidence to push back.
How to Read Each Section of Your Medicare Summary Notice
Every Medicare Summary Notice follows the same basic layout, whether it’s for Part A (hospital) or Part B (medical) services. Near the top you’ll find your Medicare number, the notice date, and the three-month period it covers. Below that sits the claims table, and at the bottom is a section explaining your appeal rights.
Understanding the Claims Detail on Your Medicare Summary Notice
Each row in the claims table shows five figures: the amount billed, the amount Medicare approved, the amount Medicare paid, any amount denied, and the maximum you may be billed. A simplified example:
| Service | Billed | Medicare Approved | Medicare Paid | You May Owe |
|---|---|---|---|---|
| Office visit | $180 | $110 | $88 | $22 |
| Blood test | $95 | $60 | $60 | $0 |
Notice that “billed” and “approved” are usually different numbers. Providers who accept Medicare assignment agree to accept the approved amount as payment in full, so the gap between billed and approved isn’t money you owe.
Common Errors to Catch on a Medicare Summary Notice
Reviewing your Medicare Summary Notice matters most when something looks off. Watch for:
- A service listed on a date you don’t recognize
- A provider you’ve never visited
- The same service billed twice
- A denial that doesn’t match what your doctor told you
Any of these can point to a simple coding mistake, or in rarer cases, someone using your Medicare number fraudulently.
How Often You’ll Receive a Medicare Summary Notice
If you have Original Medicare, a Medicare Summary arrives by mail every three months by default, though you can switch to monthly electronic notices through your MyMedicare.gov account. People enrolled only in a Medicare Advantage plan won’t get this exact form; their plan sends its own version of a claims summary instead.
What to Do If Your Medicare Summary Notice Looks Wrong
Start by calling the provider’s billing office; most mismatches turn out to be simple coding errors. If that doesn’t resolve it, call 1-800-MEDICARE, or file a formal appeal using the instructions printed on the back of your Medicare Summary Notice. You generally have 120 days from the notice date to appeal.
If your Medicare Summary Notice shows Part B premium costs that jumped because of income-related adjustments, it’s worth running your own numbers with our IRMAA Calculator before assuming something’s wrong. You generally have 120 days from the notice date to appeal, and you can find the full process on Medicare’s appeals page.
Medicare Summary Notice vs. Explanation of Benefits
People often confuse a Medicare Summary with an Explanation of Benefits, or EOB. The difference is who sends it: Medicare mails the Summary Notice for Original Medicare claims, while private insurers, including Medicare Advantage and Part D plans, send an EOB instead. The content is similar, but only Original Medicare enrollees will see the exact term “Medicare Summary Notice” on their mail.
Bottom Line: Your Medicare Summary Notice won’t ask you for money, but it will tell you exactly what Medicare paid on your behalf and give you a paper trail if anything needs correcting. Reading it each quarter, even briefly, is one of the easiest habits for staying on top of your Medicare costs.
This is for informational purposes only and isn’t financial, tax, or legal advice.

Raghu Shekar writes about personal finance, banking, Medicare, and retirement planning at SimpleUSAFinance. His goal is simple: break down the numbers people actually need — no jargon, no sales pitch — so readers can make their own decisions with confidence. When he’s not writing, he’s usually digging through the latest rate changes, tax brackets, or Medicare updates to keep the site’s calculators and guides current.