Mortgage bank statements give an underwriter a window into your real financial behavior, not just your credit score. Pay stubs and tax returns tell a lender what you earn. Mortgage bank statements tell a lender how you actually manage money, month to month. The Consumer Financial Protection Bureau’s guide to mortgage documentation outlines why lenders verify assets this closely before closing.
Most lenders request two months of statements for a conventional loan, though some loan types ask for more. Every deposit, withdrawal, and balance swing in those statements gets reviewed against the rest of your application.
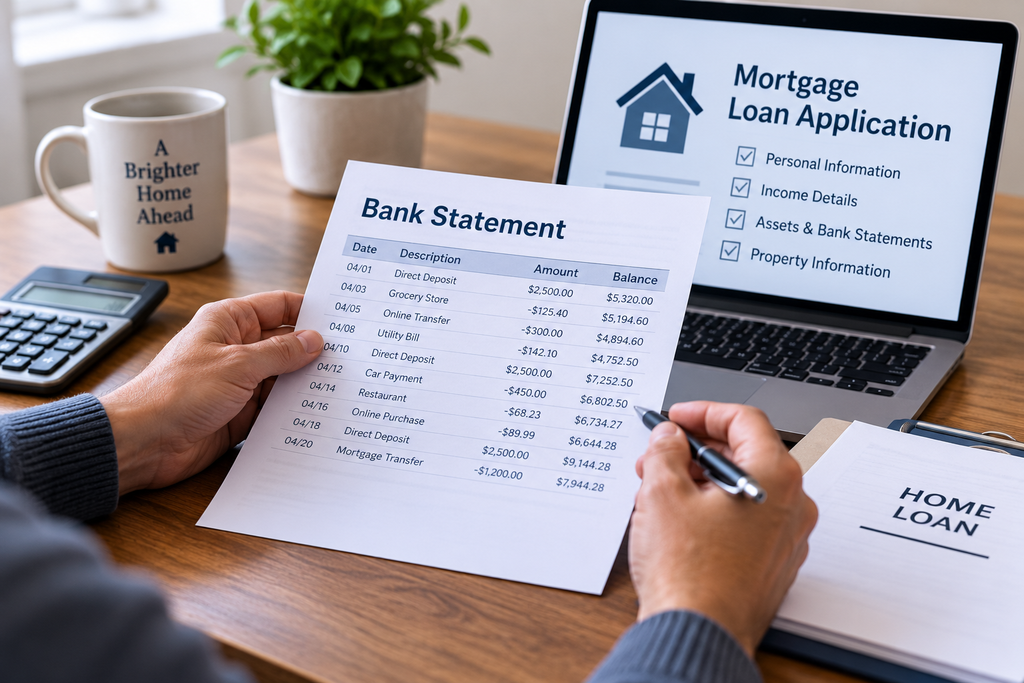
What Underwriters Actually Look For
Underwriters reviewing mortgage bank statements are checking for three things: enough money to close, a stable balance history, and no unexplained activity that contradicts your stated income.
Large or Unexplained Deposits
Any deposit that looks out of place in your mortgage bank statements will likely get flagged. As a rule of thumb, deposits over $1,000 that aren’t clearly tied to your regular payroll typically need a paper trail. That trail can be a gift letter, a sale receipt, or a simple written explanation. Fannie Mae’s Selling Guide on large deposits spells out exactly when lenders must document a deposit’s source.
This isn’t about suspicion of wrongdoing. Federal banks are also required to report any cash transaction over $10,000 under the Bank Secrecy Act, enforced by FinCEN, so a large unexplained cash deposit can trigger extra questions from both your lender and your bank.
A Quick Numeric Example: Which Deposits Get Flagged
Picture two borrowers with otherwise identical applications, each showing two months of bank statements:
- Borrower A deposits $650 from a birthday gift. Under most lenders’ $1,000 threshold, this typically passes without extra paperwork.
- Borrower B deposits $4,000 from a family loan with no note attached. This almost certainly triggers a request for a gift letter or proof of source before the loan can move forward.
The dollar amount isn’t the only factor — a $4,000 deposit that matches a documented bonus on a pay stub raises far fewer questions than the same amount with no clear origin. Context in your mortgage bank statements matters as much as the number itself.
A Quick Look at What Gets Flagged
Here’s a simple breakdown of common items in mortgage bank statements and how underwriters typically treat them:
| Item in Your Bank Statement | Underwriter Reaction |
|---|---|
| Steady payroll deposits | Confirms income, no issue |
| Deposit over $1,000, no clear source | Requires documentation |
| Cash deposit over $10,000 | Federally reported, extra scrutiny |
| NSF or overdraft fees | Raises cash flow concerns |
| Large transfer out right before closing | Requires explanation, may delay closing |
Overdrafts and NSF Fees Can Hurt More Than You Think
A single overdraft in your mortgage bank statements probably won’t sink your application. A pattern of them will. Multiple non-sufficient-funds charges signal to an underwriter that your monthly cash flow may not comfortably support a new mortgage payment.
If your recent mortgage bank statements show repeated overdrafts, it’s worth waiting a few months and building a cleaner history before you apply. Lenders read consistency as a proxy for reliability.
Self-Employed Borrowers and Bank Statement Loan Programs
Self-employed borrowers usually face closer review of their bank statements than salaried employees, since there’s no third-party pay stub confirming income. Underwriters often average deposits over 12 to 24 months of statements rather than just two, looking for a steady pattern rather than a single strong month.
There’s also a separate category worth knowing about: bank statement loans. These are designed specifically for self-employed borrowers whose tax returns understate their real cash flow after deductions. Instead of pay stubs, the lender qualifies the borrower largely off 12 to 24 months of statements directly, which makes clean, consistent deposits even more important for this group.
How to Prepare Your Bank Statements Before You Apply
The best mortgage bank statements are boring ones: steady deposits, no big unexplained transfers, and no last-minute account shuffling. A few practical steps make a real difference.
- Avoid large cash deposits in the two to three months before applying.
- Keep large gifts or fund transfers in a separate paper trail, with a dated letter if it’s a gift.
- Don’t move your down payment money between accounts right before applying; let it sit and “season” in one account.
- Pay down or pause any pattern of overdrafts well before your mortgage bank statements are pulled.
- Avoid opening new credit accounts or making large purchases that show up as big withdrawals right before closing.
None of this is about hiding anything. Clean mortgage bank statements simply mean fewer conditions, fewer delays, and a faster path to closing.
Joint Accounts and Co-Borrower Statements
If you’re applying with a co-borrower, both sets of mortgage bank statements typically get reviewed the same way. A joint account complicates things slightly, since large deposits or withdrawals from either party will show up in the same mortgage bank statements and both borrowers may need to explain them.
Keeping clear records of who deposited what, especially in a joint account, can save real time during underwriting.
Once you have a sense of what your mortgage bank statements will show, it’s worth checking how much home that actually supports. Our Mortgage Affordability Calculator can help you see a realistic monthly payment before you apply.
Frequently Asked Questions
How many months of bank statements do lenders actually need? Most conventional loans require two months. FHA and VA loans sometimes ask for the same, though self-employed borrowers or those using bank statement loan programs may need 12 to 24 months.
Do I need to explain every single deposit? No. Routine, small, or clearly payroll-linked deposits usually pass without comment. It’s the larger or unexplained ones that draw attention.
Will a single overdraft disqualify me? Not typically on its own. A repeated pattern of overdrafts across your statements is what raises real concern about cash flow.
Can I move money between my own accounts before applying? You can, but it’s better to let funds “season” in one account for at least two months rather than shuffling them right before your statements are pulled, since transfers can still require an explanation.
Bottom Line
Mortgage bank statements can quietly help or hurt your loan approval depending on how clean and consistent they look. A little preparation in the months before you apply goes a long way toward a smoother, faster closing.
This is for informational purposes only and isn’t financial, tax, or legal advice.

Raghu Shekar writes about personal finance, banking, Medicare, and retirement planning at SimpleUSAFinance. His goal is simple: break down the numbers people actually need — no jargon, no sales pitch — so readers can make their own decisions with confidence. When he’s not writing, he’s usually digging through the latest rate changes, tax brackets, or Medicare updates to keep the site’s calculators and guides current.