Finding an IRS notice in your mailbox can make your stomach drop before you’ve even opened the envelope. But most of the time, an IRS notice is routine, not a red flag, and the code printed in the corner tells you exactly what you’re dealing with.
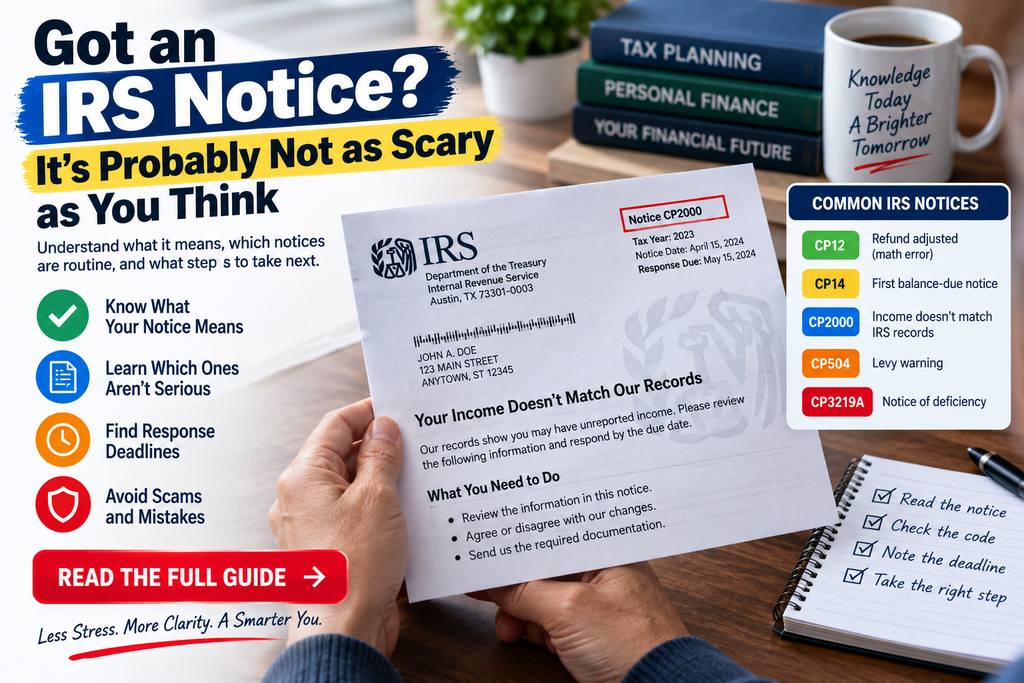
Why Getting an IRS Notice Isn’t Automatically Bad
The IRS sends over 200 million notices a year, and the overwhelming majority are computer-generated for simple reasons: a payment mismatch, a refund adjustment, or a routine reminder. An IRS notice is not the same thing as an audit. Most are resolved with a quick read and, in some cases, no response at all.
The IRS Notice Types That Aren’t Scary at All
Some of the most common notices are purely informational. A CP12 tells you the IRS corrected a math error and adjusted your refund. A CP49 lets you know your refund was applied to a past-due balance. A CP05 simply means your return is under routine review before your refund is released. None of these require you to do anything beyond reading them.
The IRS Notice Types Worth Taking Seriously
Other notices need real attention. A CP14 is the first notice you’ll get if you owe money, and it starts a 21-day clock. If it’s ignored, the IRS follows up with a CP501, then a CP503, and eventually a CP504, which is the point where the IRS can begin levying state refunds. The most serious notice, a CP3219A (Statutory Notice of Deficiency), gives you 90 days to petition Tax Court before the IRS can assess the tax on its own.
Understanding a CP2000 Notice
A CP2000 is the IRS notice people search for most, and it’s worth understanding on its own. It’s generated when your reported income doesn’t match what employers, banks, or brokerages reported to the IRS, often from an unreported 1099 for investment income or a stock sale. A CP2000 is not a bill and not an audit; it’s a proposed adjustment, and you have 30 days to agree, partially agree, or dispute it with documentation. If your CP2000 involves unreported capital gains, run the actual numbers yourself with our Capital Gains Calculator before you assume the IRS’s proposed figure is correct.
A Numeric Example: What Ignoring a CP14 Actually Costs
Say a CP14 notice arrives showing a $2,000 balance due. If you do nothing, the failure-to-pay penalty adds 0.5% of the unpaid balance per month, plus interest that compounds daily at the current federal short-term rate plus 3%. On a $2,000 balance left unpaid for six months, that can add over $100 in penalties and interest before the account escalates to a CP501, then a CP503.
The math changes fast once a CP504 arrives, since that’s the point where the IRS can move toward levying a state tax refund. Responding to the very first IRS notice, rather than waiting for the follow-ups, is almost always the cheaper path.
How to Read Any IRS Notice in Under Five Minutes
Every IRS notice follows the same layout. The notice number (CP or LTR, followed by digits) sits in the top corner and tells you exactly what type it is. Below that is the reason for the notice, the amount involved if any, and a response deadline calculated from the date printed on the letter, not the day it arrives in your mailbox.
| Notice | What It Means | Typical Deadline |
|---|---|---|
| CP12 | Refund adjusted for a math error | Informational only |
| CP14 | First balance-due notice | 21 days |
| CP2000 | Income doesn’t match third-party reports | 30 days |
| CP504 | Levy warning if balance stays unpaid | 30 days |
| CP3219A | Formal notice of deficiency | 90 days |
How to Respond to an IRS Notice
If you agree with what the notice says, follow the payment or correction instructions printed on it. If you disagree, respond in writing before the deadline with copies of supporting documents, never the originals. If a notice involves a retirement account distribution that looks off, check it against our RMD Calculator before you reply, since a mismatched 1099-R is a common trigger for these letters.
Keep a copy of everything you send, along with proof of mailing if you respond by paper. If the deadline is close, calling the number on the notice to confirm receipt of your response can prevent an automatic escalation while your paperwork is still in transit.
IRS Notices vs. Scam Letters and Calls
Real IRS notices arrive by mail, never by phone, text, or email demanding immediate payment. The IRS never asks for payment by gift card, wire transfer, or cryptocurrency. If you get a call or message claiming to be the IRS threatening arrest, that’s a scam, not a real IRS notice.
Scammers also mail fake letters designed to look official. A genuine notice always includes a notice or letter number in the upper corner that you can look up directly on IRS.gov — if a mailed letter demands payment through an unusual method or skips that notice number entirely, treat it as suspicious and verify independently before responding.
Frequently Asked Questions
Does getting an IRS notice mean I’m being audited? No. Most notices are routine corrections or reminders. Only a small share relate to an actual audit, and those are typically labeled as an examination notice rather than a standard CP notice.
What happens if I can’t pay what a notice says I owe? The IRS offers payment plans for many balances. Responding by the deadline, even to request a plan, is far better than letting the notice go unanswered and escalate.
Can I call the IRS instead of responding in writing? For simple questions, yes — the notice includes a phone number. But if you’re disputing the notice’s findings, a written response with documentation creates a paper trail that a phone call doesn’t.
How long should I keep IRS notices after resolving them? Keep copies of any notice and your response for at least three years, matching the general period the IRS has to audit a return, longer if the notice involved a significant adjustment.
Bottom Line
An IRS notice usually means less than it feels like in the moment — most are routine, and the ones that matter are easy to spot once you know what the notice number is telling you. Read it carefully, note the deadline, and respond before it escalates.
This is for informational purposes only and isn’t financial, tax, or legal advice.

Raghu Shekar writes about personal finance, banking, Medicare, and retirement planning at SimpleUSAFinance. His goal is simple: break down the numbers people actually need — no jargon, no sales pitch — so readers can make their own decisions with confidence. When he’s not writing, he’s usually digging through the latest rate changes, tax brackets, or Medicare updates to keep the site’s calculators and guides current.