Most people assume charitable giving and taxes work together automatically: you give, you deduct, you save. That’s not how it works anymore. Under the 2026 tax rules, charitable giving and taxes only intersect in specific, calculable ways, and knowing which ones apply to you is the difference between a real tax break and a donation that saves you nothing.
Understanding charitable giving and taxes starts with one question: do you take the standard deduction or do you itemize? The answer changes everything else in this article, and it’s worth answering honestly before you make any large gift this year.
Why Charitable Giving and Taxes Don’t Always Line Up
For years, charitable giving and taxes only connected if you itemized deductions, and most taxpayers don’t. In 2026, the standard deduction is $16,100 for single filers and $32,200 for married couples filing jointly. Unless your mortgage interest, state taxes, and donations combined exceed that number, itemizing gets you nothing extra.
That’s why so many people believe their giving has zero effect on their tax bill. For most of the last decade, that belief was correct for the majority of filers, since claiming the standard deduction meant donations simply didn’t show up on the return at all. Starting in 2026, it’s only partly true, which is the whole reason charitable giving and taxes deserve a fresh look this year. The rules didn’t just change slightly, they changed enough that last year’s giving strategy may no longer be the right one.
Charitable Giving and Taxes When You Take the Standard Deduction
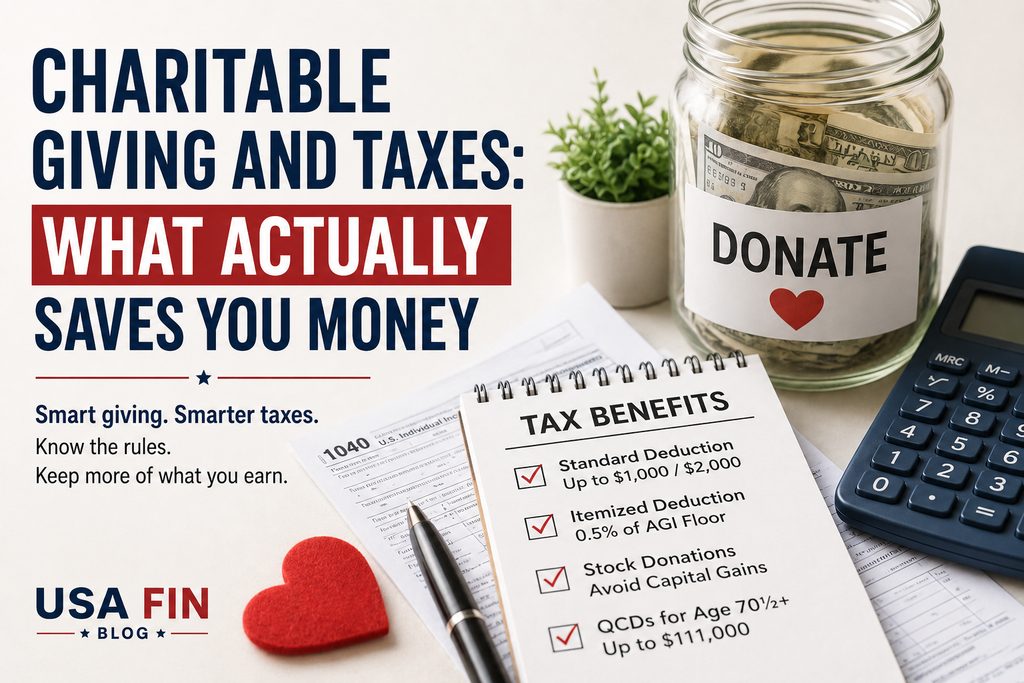
Here’s the biggest change: starting in the 2026 tax year, taxpayers who take the standard deduction can also deduct cash donations to qualified charities, up to $1,000 for single filers or $2,000 for married couples filing jointly. This is a new above-the-line deduction, meaning it reduces your taxable income even if you never itemize.
This single change reshapes charitable giving and taxes for roughly 144 million American filers who don’t itemize. The catch: it only covers cash gifts (checks, credit cards, payroll deductions, online donations) made directly to qualified 501(c)(3) public charities. Donor advised funds, private foundations, and non-cash gifts like clothing or property don’t qualify for this particular deduction, so it’s worth checking that your usual giving method actually counts before you rely on it.
If you give small, regular amounts through your church, a local food bank, or a national charity by credit card, this is likely the version of charitable giving and taxes that applies to you. There’s no form to fill out beyond keeping your receipts; tax software applies the deduction automatically once you confirm you’re taking the standard deduction.
Charitable Giving and Taxes When You Itemize
If you do itemize, charitable giving and taxes work differently in 2026 than they did before. A new rule requires your charitable contributions to exceed 0.5% of your adjusted gross income before any of them count toward your itemized deduction. If your AGI is $200,000, the first $1,000 of giving doesn’t reduce your taxes at all; only the amount above that floor does.
This changes the math on charitable giving and taxes for itemizers with modest annual giving. Someone who donates $3,000 a year on a $200,000 AGI only gets a deductible amount of $2,000 once the 0.5% floor is subtracted. Someone who bunches several years of giving into one tax year clears the floor more easily and keeps more of the deduction. The floor applies every year you itemize, so it’s not a one-time adjustment, it’s a permanent feature of how charitable giving and taxes now interact for anyone who itemizes going forward.
Sample Charitable Giving and Taxes Example: Bunching Donations
| Scenario | Annual giving | AGI | Deductible after 0.5% floor |
|---|---|---|---|
| Giving spread evenly | $3,000/year | $200,000 | $2,000/year |
| Giving bunched every 2 years | $6,000 in year one, $0 in year two | $200,000 | $5,000 in year one |
Bunching two years of gifts into one year is one of the few moves that meaningfully changes charitable giving and taxes in your favor, since it lets more of your total giving clear the AGI floor at once.
Charitable Giving and Taxes for High Income Earners
For taxpayers in the top 37% bracket, charitable giving and taxes come with an additional limit in 2026. The value of the itemized charitable deduction is capped at 35%, even though the top marginal rate is 37%. In plain terms, a dollar donated by a high earner now saves 35 cents in tax, not 37 cents.
This cap doesn’t erase the benefit of giving, but it does mean charitable giving and taxes no longer scale in a straight line for the highest earners. Combined with the 0.5% AGI floor, high income donors typically get the most value from larger, deliberate gifts rather than frequent small ones. A donor in this bracket who wants to keep charitable giving and taxes working in their favor usually benefits from planning gifts with a tax advisor rather than giving reactively at year end.
Charitable Giving and Taxes: Donating Stock vs. Cash
Cash isn’t always the most tax efficient way to give. Donating appreciated stock you’ve held for more than a year lets you deduct the full fair market value while avoiding the capital gains tax you’d owe if you sold it first. This is one of the clearest wins in charitable giving and taxes for anyone holding investments that have grown significantly in value.
Deduction limits differ by asset type. Cash gifts can offset up to 60% of your AGI in a given year, while gifts of appreciated stock or property are capped at 30% of AGI. Charitable giving and taxes involving non-cash assets also require more documentation, including a qualified appraisal for larger gifts of property. Anyone weighing stock versus cash should run both scenarios, since the gap between them is one of the largest single levers in charitable giving and taxes for investors specifically.
Charitable Giving and Taxes After Age 70½: Qualified Charitable Distributions
If you’re 70½ or older and hold a traditional IRA, a Qualified Charitable Distribution (QCD) is often the single most efficient way to combine charitable giving and taxes. A QCD lets you transfer up to $111,000 directly from your IRA to a qualified charity in 2026, and that amount never counts as taxable income in the first place.
Because a QCD reduces your AGI directly rather than working through the deduction rules above, it sidesteps the 0.5% floor, the 35% cap, and the standard versus itemize decision entirely. For retirees who don’t need every dollar of their required IRA distribution, this is often where charitable giving and taxes intersect most cleanly, since the tax benefit happens automatically the moment the transfer is made. Run your own charitable giving and taxes numbers with our Charitable Deduction Calculator to see which approach saves you the most before you file.
Bottom Line: Charitable Giving and Taxes
Charitable giving and taxes only combine into real savings when you match your giving method to your tax situation: the new non-itemizer deduction if you take the standard deduction, bunching or stock gifts if you itemize, and QCDs if you’re 70½ or older with a traditional IRA. Run the numbers before you give, not after, since the same donation can be worth very different amounts depending on how you make it.
This is for informational purposes only and isn’t financial, tax, or legal advice.

Raghu Shekar writes about personal finance, banking, Medicare, and retirement planning at SimpleUSAFinance. His goal is simple: break down the numbers people actually need — no jargon, no sales pitch — so readers can make their own decisions with confidence. When he’s not writing, he’s usually digging through the latest rate changes, tax brackets, or Medicare updates to keep the site’s calculators and guides current.