Building an emergency fund when money is tight can feel like being told to save water during a drought. Every financial guide assumes you have room to spare, and when your paycheck barely covers rent, groceries, and gas, that advice can feel out of touch. But an emergency fund when money is tight isn’t about hitting some perfect number fast. It’s about building a small buffer that keeps one bad week from turning into a bad year.
Here’s a realistic way to build an emergency fund when money is tight, even if you’re starting from zero, without pretending your situation looks like the version most budgeting advice assumes.
Why an Emergency Fund When Money Is Tight Still Matters
When cash is already stretched, a car repair or a missed shift can force a choice between a credit card and going without. An emergency fund when money is tight doesn’t need to cover six months of expenses to help. Even a few hundred dollars can be the difference between paying cash for a flat tire and paying interest on it for a year.
The goal of an emergency fund when money is tight isn’t perfection. It’s having something between you and the next unexpected bill, so a small crisis doesn’t become a debt spiral.
The Real Cost of Having No Buffer at All
Without any buffer at all, a single $400 surprise expense commonly gets pushed onto a credit card. At an average card APR near 20%, carrying that $400 for a year at minimum payments can add $70 to $90 in interest alone, turning a one-time problem into an ongoing one. That’s the real cost an emergency fund when money is tight is meant to prevent, and it’s why even a small buffer changes the math so much.
How Much You Actually Need for an Emergency Fund When Money Is Tight
Most financial advice says to save three to six months of expenses. If money is already tight, that number can feel so far away it stops you from starting at all. Set that target aside for now.
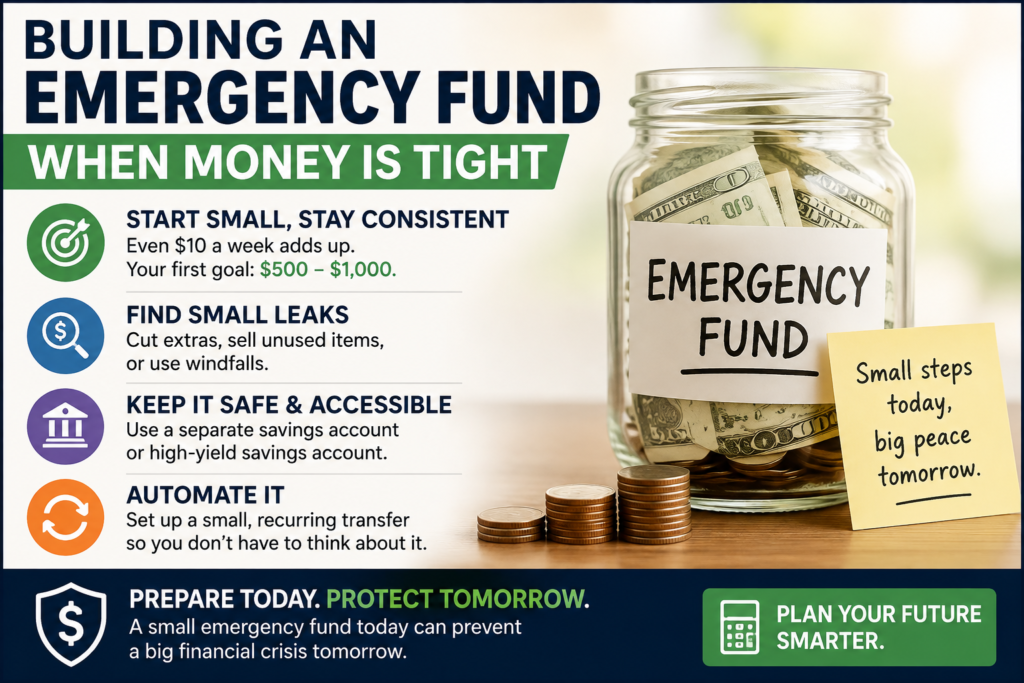
A more useful first goal for an emergency fund when money is tight is $500 to $1,000. That covers most common surprises: a car repair, a broken appliance, an unexpected copay. Once you hit that number, you can decide whether to build further or shift focus to paying down debt.
A Small Emergency Fund When Money Is Tight, Broken Down by Week
Here’s what building a $500 buffer looks like over different timeframes:
| Weekly Amount | Weeks to $500 |
|---|---|
| $10 | 50 weeks |
| $20 | 25 weeks |
| $35 | about 14 weeks |
| $50 | 10 weeks |
None of these numbers require a windfall. Building an emergency fund when money is tight requires finding a small, repeatable amount and sticking with it, even when it feels too small to matter. Someone saving just $15 a week reaches $500 in under nine months without ever making a single large deposit.
What Actually Counts as an Emergency
An emergency fund when money is tight is only useful if you’re also clear on what actually counts as an emergency. A job loss, a medical bill, an urgent car or home repair, or a family crisis all qualify. A sale you don’t want to miss, a routine expense you simply forgot to budget for, or a vacation opportunity do not, even if they feel urgent in the moment. Drawing this line clearly before you’re in a stressful situation makes it much easier to actually use the fund correctly instead of second-guessing yourself when a real emergency hits.
Where to Find Money for an Emergency Fund When Money Is Tight
When there’s no obvious extra cash, building an emergency fund when money is tight comes down to finding small leaks rather than making one big cut. A few places worth checking:
- Subscriptions you forgot you’re paying for
- A cheaper cell phone plan or provider switch
- Selling one or two unused items around the house
- Rounding up purchases and saving the difference
- Any windfall: a tax refund, rebate, or cash gift, before it gets absorbed into regular spending
None of these alone will fund the goal overnight. Together, they add up faster than most people expect, and reviewing even one recurring subscription can free up $10 to $20 a month toward the goal, which alone can reach the $500 mark within a year.
Common Mistakes to Avoid
A common mistake when building an emergency fund when money is tight is treating a windfall, like a tax refund, as spending money by default instead of asking whether it should go toward the fund first. Redirecting even half of a typical $2,000 to $3,000 refund can single-handedly fund the entire first goal in one move, without touching a single regular paycheck.
A second common mistake is trying to build an emergency fund and pay off high-interest debt at exactly the same pace, splitting limited money so thin that neither goal moves quickly. A more realistic order is a small starter cushion of $500 to $1,000 first, then aggressive debt payoff, then building the emergency fund when money is tight back up further once high-interest balances are cleared. A third mistake is keeping the money somewhere too easy to reach, like the same checking account used for daily spending, which quietly erodes the fund a few dollars at a time until it’s gone.
Where to Keep an Emergency Fund When Money Is Tight
Keep this money somewhere separate from your everyday checking account, so it’s not an easy tap for non-emergencies. A basic savings account at your existing bank works fine to start building an emergency fund when money is tight.
A high yield savings account is worth considering once you have a little momentum, since it earns more than a standard savings account while still letting you withdraw the money quickly if you need it. The point of an emergency fund when money is tight is access, not growth, so avoid anything that locks your money up or penalizes withdrawals, like a CD. Money market accounts are another reasonable middle ground, often paying a similar rate to a high-yield savings account while sometimes including check-writing or debit access for true emergencies.
Automating an Emergency Fund When Money Is Tight
The single biggest predictor of whether an emergency fund when money is tight actually gets built is whether it’s automatic. Setting up a small, recurring transfer, even $10 a week, removes the decision from your plate every payday.
Automation also protects the effort from good intentions that don’t survive a busy week. If the transfer only happens when you remember to do it manually, it often doesn’t happen at all. Many banks let you schedule this transfer for the same day your paycheck lands, so the money moves before it has a chance to get spent elsewhere, which makes an emergency fund when money is tight far more likely to actually get built.
What to Do If You Can’t Save Anything Right Now
If there’s truly nothing left after essentials, building an emergency fund when money is tight may need to wait a pay cycle or two, and that’s not a failure. Focus first on any bills that carry late fees or shutoff risk, then revisit savings once the immediate pressure eases. Once those pressures ease, even resuming at half your original amount keeps an emergency fund when money is tight moving instead of stalled indefinitely.
Even $5 a week, resumed as soon as you can manage it, keeps the habit of an emergency fund when money is tight alive without adding stress to a month that’s already stretched thin. If you want to see how a small weekly amount adds up over time, run your own numbers through our Emergency Fund Calculator to compare short term saving against longer term goals.
Bottom Line
An emergency fund when money is tight doesn’t need to start big or grow fast to be useful. Start with whatever amount you can automate consistently, aim for $500 to $1,000 first, and let the habit of building an emergency fund when money is tight grow from there. The point is progress you can sustain, not a number you hit once and forget, and that mindset matters more than the exact dollar figure you land on this month.
This is for informational purposes only and isn’t financial, tax, or legal advice.

Raghu Shekar writes about personal finance, banking, Medicare, and retirement planning at SimpleUSAFinance. His goal is simple: break down the numbers people actually need — no jargon, no sales pitch — so readers can make their own decisions with confidence. When he’s not writing, he’s usually digging through the latest rate changes, tax brackets, or Medicare updates to keep the site’s calculators and guides current.
Pingback: The 50/30/20 Budget Rule Explained With Real Numbers